Focused arrival windows
Useful updates and clear arrival timing.
Most Houston roof insurance claims start the same way: a storm passes, the roof is damaged, and nobody explains what happens next. This guide explains the process in plain language — ACV vs RCV, deductibles, adjuster meetings, supplements and denials — and where a roofer's job ends and yours begins. We are not a public adjuster, we do not negotiate claims, and we cannot guarantee that your claim will be approved.
Useful updates and clear arrival timing.
Review the approach and price before deciding.
Equipped vehicles and respectful cleanup.
Neighbors serving neighbors with follow-through.
Six things every Houston homeowner should understand before they file, or before they meet an adjuster.
Actual cash value and replacement cost value are two different numbers, and the gap between them is what you pay until the work is done.
On an RCV policy, the insurer pays ACV first and releases the depreciation only after the work is completed and documented.
The homeowner must pay it. Texas law bars a contractor from waiving, rebating or absorbing it.
What happens when the adjuster inspects, what we do at that meeting, and what we do not do.
What a supplement is, what a denial means, and what your options are when the first answer is no.
Most of Houston is outside the windstorm catastrophe area. Only Harris County east of SH 146 is in it.
Share what is happening and receive a clear next step from the local team.
A roof insurance claim in Texas follows a sequence: document the damage, file the claim, meet the adjuster, get a settlement, do the work, and then — on an RCV policy — collect the recoverable depreciation. Each step has its own rules, and the rules are in your policy, not on this page.
The first distinction is ACV vs RCV. On a replacement-cost-value policy, the insurer typically pays actual cash value first — replacement cost minus depreciation — and releases the recoverable depreciation only after the work is completed and documented. On an ACV-only policy there is no second payment. That gap is the reason a homeowner can be told a roof is covered and still have to pay thousands out of pocket until the work is done. Ask your insurer which one your policy is, and get the answer in writing.
The second distinction is the filing deadline, and here we will not give you a single number, because the sources do not agree on one. A two-year framing, a one-year TWIA and policy framing, and “depends on your policy” all appear in the sources. Do not take a deadline from a roofing website, including this one. Check your policy, and check it early.
We inspect the roof, photograph every damaged area as found, and note the storm date. You get the photos and a written scope.
You file with your insurer, with the photos and the scope in hand. The claim number and the adjuster's name are yours to keep.
The adjuster inspects. We are there with the photos and the scope to answer questions about what we found. We do not negotiate the claim.
The insurer pays ACV first on an RCV policy. The recoverable depreciation follows after the work is completed and documented.
The repair is done as the scope says, documented with photos, and the completion paperwork goes to the insurer for the depreciation release.
Every damaged area photographed as found, with the storm date noted. The photos are yours, whether or not you claim.
A written scope naming the damage, the repair and the price, so the adjuster can see exactly what the work is.
We meet the adjuster on site with the photos and the scope, and answer questions about what we found.
When the inspection finds more damage than the first scope covered, we put the addition in writing with photos.
Photos of the finished work, so the depreciation release has the documentation the insurer asks for.
We scope the damage we can show in photos. A padded scope helps nobody: it slows the claim and puts the homeowner at risk.
We do not act as a public adjuster, we do not negotiate claims, and we do not speak for you to your insurer. That is the law, and we follow it.
We cannot guarantee that your claim will be approved. Any roofer who guarantees approval is promising something they do not control.
Texas law bars a contractor from waiving, rebating or absorbing a deductible. We will not offer it, and you should refuse any roofer who does.
The sources do not agree on a single filing deadline, so we do not state one. Check your policy, and check it early.
We inspect and photograph the damage as found, and put the repair in a written scope, so you file with the facts in hand.
A denial is not the end of the story, but it is a policy question, not a roofing question. We can document the damage again with photos and a written scope. Whether to appeal is a decision for you and, if you want one, a public adjuster or a lawyer — not your roofer.
We meet the adjuster on site with the photos and the scope, and answer questions about what we found. We do not negotiate the claim.
On an RCV policy, the recoverable depreciation follows after the work is completed and documented. If the gap is bigger than depreciation, ask your insurer for the scope in writing and compare it with ours, line by line.
Houston's claims follow its storms, and each storm leaves a different file. Harvey, the May 2024 derecho and Hurricane Beryl each produced a different kind of claim, and the file has to match the storm.
154,170 homes flooded in Harris County. Flood claims and roof claims are different policies with different rules — a roof claim does not cover flood water, and a flood claim does not cover wind damage to the roof.
Straight-line winds near 100 mph through downtown, the Heights, Timbergrove and EaDo. Wind claims: lifted shingles, torn ridges, limb impact, all photographed as found.
Gusts of 83 mph at IAH and 84 mph at Hobby. Wind and tree claims, with the storm date a matter of record.
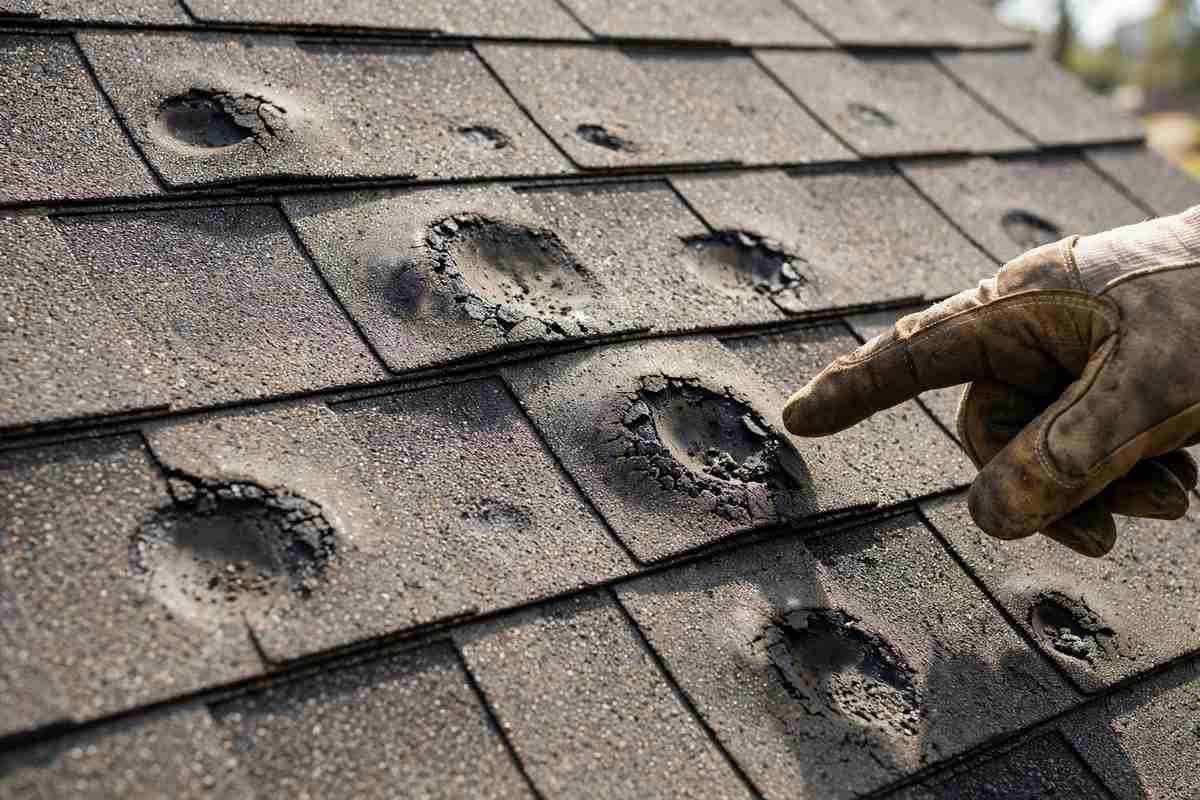
Hail season peaks in May. Hail claims need impacts photographed while they are fresh, because granule loss washes away with the next rains.
Only Harris County east of SH 146 is in the catastrophe area, inside La Porte, Morgan's Point, Pasadena, Seabrook and Shoreacres. Most Houston homes are not TWIA homes.
Coastal wind claims, where Ike gusted over 100 mph in 2008. Wind uplift is the claim here, and the file needs to show the uplift, not just the missing shingles.
Deferred Harvey moisture: underlayment and decking that softened after days of standing water, and did not show for months. The file has to show the deck, not just the shingles.
Not listed? Bellaire, West University Place, Humble and Jersey Village are separate cities, not Houston neighbourhoods, and are not listed here. Call (936) 873-7200 and we will confirm coverage for your address.
A homeowner whose first claim was not approved for roof repair, after the first adjuster met with another roofing company.
A second inspection with photos and a written scope, and a meeting with a different adjuster, got the roof replacement approved. The documentation, not the argument, changed the answer.
Afterwards: Keep the photos and the scope from the first inspection. A second look needs the same file, not a new story.
Hail damage photographed the week of the storm, with every impact documented and the storm date noted.
The claim was filed with the photos and the scope in hand, and the adjuster could see the damage instead of hearing about it.
Afterwards: Inspect soon after the storm. Hail impacts are clearest while they are fresh.
A repair that found more damage once the roof was opened: soft decking under shingles that had looked sound.
The addition was put in writing with photos and submitted as a supplement, so the claim matched the work actually needed.
Afterwards: Supplements are normal. They are paperwork with photos, not a fight.
These are the claim problems Houston homeowners bring us most. We help with the documentation and the scope. The claim itself is yours and your insurer's.
A denial is a policy question. We can document the damage again with photos and a written scope. Whether to appeal is a decision for you and, if you want one, a public adjuster or a lawyer — not your roofer.
On an RCV policy, the insurer pays ACV first and releases the recoverable depreciation only after the work is completed and documented. On an ACV-only policy there is no second payment. We explain the difference; your policy says which one you have.
Texas law bars a contractor from waiving, rebating or absorbing a deductible. Any roofer who offers to cover it is offering to break the law, and the homeowner is the one at risk.
A claim without photos is a claim without proof. We photograph the damage as found, note the storm date, and put the repair in a written scope — the three things an adjuster needs.
Texas has no state roofing licence, so there is no licence number to show you. What we can show you is a real address, real Google reviews, photos of your own roof, and a written scope before any work starts.
Claims in Houston are storm claims, and the crew that documents yours should know which storm hit your neighbourhood and what it does to the roofs there.
Excerpts from our Google reviews, shown with the reviewer’s name, star rating and the date Google shows. Our full rating is 4.9 out of 5 across 46 Google reviews. See all reviews on Google.
★★★★☆
I had storm damage on my roof, and after the first insurance adjuster met with another roofing company, the claim was not approved for roof repair. My niece suggested i call Johnathan, and he came out, met with a different adjuster, and helped get the roof replacement approved.
★★★★★
From our first call with Thomas Family Roofing, it was clear they were focused on giving us a quality new roof and making the whole roofing process easy to understand. Miguel explained the scope of the roof replacement, the materials and shingle options...
★★★★★
We contacted Thomas Family Roofing for an estimate on repairs for our metal roof in Houston. Luis came out, inspected the roof in person, and explained clearly what needed attention, including a few details about flashing and panel areas that other roofers had missed.
ACV is actual cash value: replacement cost minus depreciation. RCV is replacement cost value: what the repair actually costs. On an RCV policy, the insurer typically pays ACV first and releases the recoverable depreciation only after the work is completed and documented. On an ACV-only policy there is no second payment. Ask your insurer which one your policy is, and get the answer in writing.
We do not state a single deadline, because the sources do not agree on one: a two-year framing, a one-year TWIA and policy framing, and “depends on your policy” all appear. Do not take a deadline from a roofing website, including this one. Check your policy, and check it early.
No. It is illegal for a contractor to waive, rebate or absorb a homeowner's deductible under Texas Insurance Code Chapter 707 and Business and Commerce Code section 27.02. The law carries penalties of up to a $2,000 fine and six months in jail, and a roofing contract must include the deductible notice the law requires.
Probably not. The Texas Windstorm Insurance Association covers only the designated catastrophe area: 14 coastal counties plus Harris County east of SH 146, inside La Porte, Morgan's Point, Pasadena, Seabrook and Shoreacres. Most Houston homes have wind and hail in their standard homeowners policy instead. Check your policy, not a roofing website, for your coverage.
Not seeing your question? Call the local team and ask it directly.
Ask the local team
Wind and storm damage documented with photos, then repaired on a written scope.
View service
Hail bruising and cracked shingles inspected and documented for your claim file.
View service
Full tear-off and replacement when repair no longer makes sense, with the deck inspected first.
View service
A full walk of the roof and attic with photos, so you can see what is wrong before you decide anything.
View service
Call (936) 873-7200 and tell us what you are seeing. We will arrange an inspection, show you photos of the roof, and put the scope in writing before any work starts. Phone is the only way to reach us — there is no email address published for this business.